Early October 2026 has delivered one of the clearest demand signals of the year for the construction additives industry: India’s construction chemicals market has crossed INR 24,435 crore (approximately USD 2.9 billion) in FY2026, according to new analysis from Makreo Research and Consulting published on October 3. The report projects the market will exceed INR 34,872 crore (roughly USD 4.1 billion) by FY2031, a compound annual growth rate of 7.37%. For manufacturers and exporters of cellulose ethers, redispersible polymer powder (RDP), and polycarboxylate superplasticizers (PCE), India is no longer just a fast-growing story – it is becoming the demand anchor of the Asia-Pacific additive trade.
The Numbers Behind India’s FY2026 Milestone
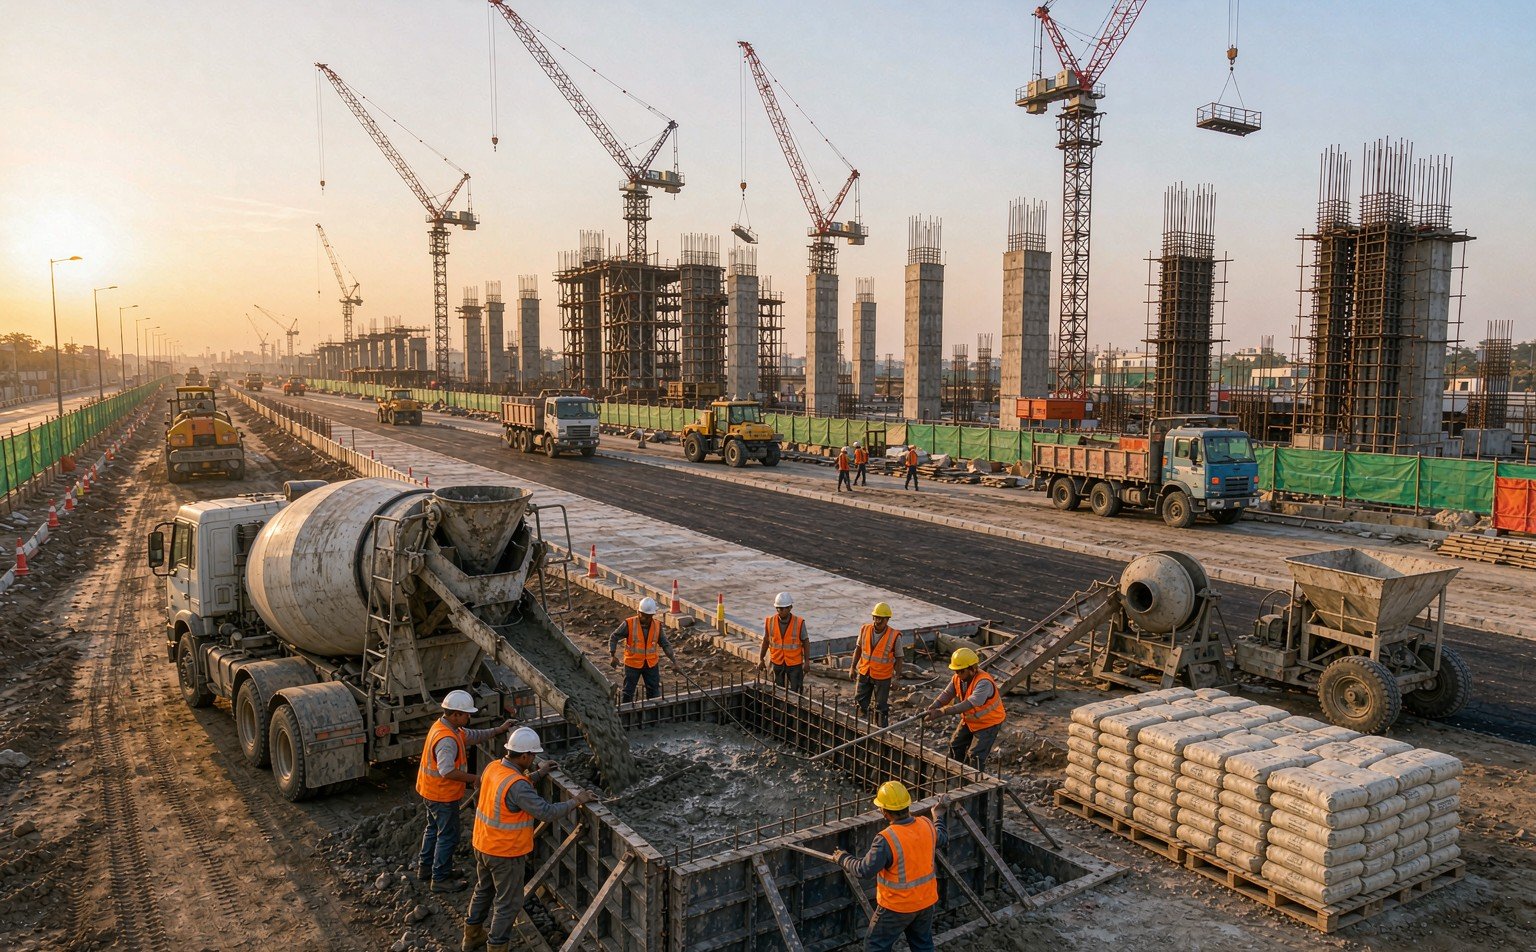
The scale of India’s infrastructure pipeline underpins the entire forecast. The Union Budget 2026-27 raised public capital expenditure to INR 12.2 lakh crore, with continued spending across transport corridors, affordable housing, water infrastructure, urban mobility, and industrial parks. Every category of that spending – roads, metro rail, ports, residential towers – pulls through concrete admixtures, waterproofing systems, tile adhesives, and repair mortars.
According to the Makreo analysis, demand is also shifting in quality, not just quantity. Project owners increasingly specify products that reduce maintenance cycles, improve durability, and lower lifecycle costs, moving procurement conversations away from lowest-price commodity supply toward performance-documented systems. That shift favors technically capable additive suppliers over trading houses.
Admixtures and Waterproofing Lead Product Demand
By product category, the FY2026 market breaks down with a clear hierarchy:
- Concrete admixtures: approximately 32% of market value – the largest category, driven by ready-mix concrete adoption and high-performance PCE-based superplasticizers on infrastructure packages
- Waterproofing chemicals: around 30% – lifted by metro tunneling in Mumbai and Delhi, basement and roof systems, and tighter durability codes from the Bureau of Indian Standards (BIS)
- Adhesives and sealants, repair and rehabilitation chemicals, and protective coatings covering the remaining share
Industry trackers note that crystalline waterproofing systems are capturing premium specification slots in underground construction, as asset owners demand warranty-backed water-tightness rather than membrane-dependent solutions. Coastal infrastructure in Maharashtra and Gujarat – where chloride exposure is aggressive – is pushing BIS-certified admixture formulations into tenders that previously accepted unbranded material.
Dry-Mix Mortar: The Volume Engine for Cellulose Ethers and RDP
For HPMC and RDP producers specifically, the most important structural trend is India’s accelerating shift from site-mixed sand-cement to factory-blended dry-mix mortar. Mordor Intelligence sizes the India dry-mix mortar market at 10.28 million tons in 2025, rising to 10.95 million tons in 2026, and reaching 14.98 million tons by 2031 – a 6.48% CAGR. Grand View Research puts the market at USD 4.47 billion in 2025, heading to USD 7.50 billion by 2033, noting that India accounts for 8.1% of the global market and is the fastest-growing regional market in Asia-Pacific.
The application mix within that volume matters for additive dosage rates:
- Plaster remains the largest application at 32.10% of 2025 volume, anchored by affordable housing programs under Pradhan Mantri Awas Yojana (PMAY-Urban)
- Tile adhesives are forecast to grow at a 7.12% CAGR through 2031, the fastest of the major applications, as large-format tile trends push polymer and cellulose ether dosages upward
- Commercial construction is the fastest-growing end-use sector at 7.35% CAGR, while residential still holds 52.02% of volume
- Self-leveling underlayments and waterproofing slurries are displacing semi-dry screeds in premium commercial flooring across Bengaluru, Hyderabad, and Pune
Each ton of factory-blended tile adhesive or ETICS render carries roughly 0.3-0.5% HPMC and 2-4% RDP by weight – meaning India’s mortar volume growth translates almost linearly into imported additive demand.
Local Supply Chains Are Scaling – But Not Enough
India’s domestic upstream capacity is expanding, and global suppliers should read this correctly. On September 17, 2026, Asian Paints began commercial production at its new VAE emulsion plant in Dahej, Gujarat, with 150,000 tons per year capacity – a meaningful boost to India’s upstream supply of a key RDP raw material, though the output flows mostly to the company’s own paint operations rather than the open mortar market.
Consolidation is also reshaping the competitive field. BirlaNu has announced an INR 500 crore investment program placing construction chemicals alongside its pipes business, Berger Paints has built a sizeable waterproofing arm, and Tri Polarcon’s acquisition of Rockhard Polycoats added industrial flooring and repair capabilities. Yet even with these moves, India remains a structural net importer of construction-grade cellulose ethers and VAE-based RDP powder. China still supplies an estimated 50-55% of global cellulose ether tonnage, and no commercial-scale Indian HPMC capacity is positioned to displace imported material in the near term.
Import Dynamics and the Q4 2026 Price Picture
Price dynamics through the fourth quarter favor buyers who move early. Regional VAE RDP benchmarks show the arbitrage clearly: Chinese material trades near USD 1.48-1.70/kg, Indian landed prices sit around USD 1.96-2.18/kg, while German and US product holds at USD 2.54-2.76 and USD 2.10-2.32 per kg respectively. Meanwhile, Wacker Chemie raised prices for its polymer powders and dispersions by up to 15% across European and US plants during 2026, a signal of cost inflation that keeps imported Asian powder competitive in specification-driven segments.
On the PCE side, September’s Chinese monomer rally – driven by ethylene glycol prices up 25.6% month-on-month and tight EO supply – has started to cool, with October forecasts pointing to weak-fluctuation trading as downstream buyers digest inventories. For Indian admixture blenders importing HPEG and TPEG monomers, the window suggests stable-to-softer input costs through the peak construction season.
What Buyers and Formulators Should Watch in Q4 2026
- BIS certification under IS 15477 for tile adhesives and grouts is now enforced in tender documentation in Gujarat and Tamil Nadu – suppliers without certified formulations are exiting specification channels
- Lock RDP and VAE contracts before year-end, when Q4 restocking and India’s peak construction pace typically tighten spot availability
- MHEC substitution is gaining ground in India’s render and gypsum segments as a cost-effective alternative where specifications allow
- Second-source qualification of both HPMC and RDP is becoming standard procurement practice as buyers de-risk supply chains
- Green-building credit systems (GRIHA, IGBC) are beginning to reward low-VOC, documented-carbon additive formulations
Conclusion
India’s construction chemicals market crossing INR 24,435 crore is more than a headline number – it confirms a durable, infrastructure-led demand cycle that will pull cellulose ethers, RDP, and PCE imports higher through FY2031. Suppliers who combine certified product documentation, competitive ex-China pricing, and technical formulation support are best positioned to capture that growth.
Looking for a reliable supply partner for the Indian and global dry-mix mortar market? Hosechem supplies HPMC, HEMC, HEC, redispersible polymer powder (RDP), and PCE superplasticizer monomers to mortar producers, tile adhesive manufacturers, and construction chemical formulators worldwide – with consistent viscosity grades, stable supply, and export documentation ready for BIS-compliant formulations. Contact Hosechem today to request samples and a customized quotation for your Q4 2026 procurement program.